
How Independent Agents Streamline Insurance With Choice And Care
Most people stuck with captive agents don’t realize they’re paying more for less choice. At Heaton Bennett Insurance, we’ve seen firsthand how independent agents deliver better rates, wider coverage options, and genuine loyalty to their clients instead of insurance companies.
How independent agents work is fundamentally different. They compare policies across multiple carriers in minutes, find gaps in your coverage you didn’t know existed, and actually answer the phone when you need them.
Why Independent Agents Win on Price and Service
One Carrier Limits Your Options and Your Wallet
Captive agents work for one insurance company, which means they operate within that carrier’s rates, products, and profit margins. Independent agents represent five to eight different insurance companies, giving them the power to shop your coverage across multiple carriers simultaneously. When independent agents compare policies for a client, they are not limited to one company’s offerings or pricing strategy. A client shopping for homeowners insurance might find that Company A offers the best rate on dwelling coverage, Company B provides superior liability protection at a lower cost, and Company C has the most competitive deductible structure. Captive agents cannot offer this flexibility, so their clients pay whatever that single company charges.
Competition between carriers forces pricing discipline that captive agents never experience. Independent agents leverage this competition to negotiate better rates because they can move business to rival carriers if pricing becomes uncompetitive. Captive agents have zero incentive to push back on their employer’s rates, so clients absorb the cost difference.
Service That Answers to You, Not Corporate Headquarters
Captive agents answer to corporate headquarters and must follow strict sales protocols and commission structures that prioritize the parent company’s bottom line, not yours. When you call a captive agent with a coverage question or a claim issue, they work within constraints set by their employer, which often means slower responses and limited problem-solving authority. Independent agents answer directly to clients because their reputation and income depend entirely on client satisfaction and retention.
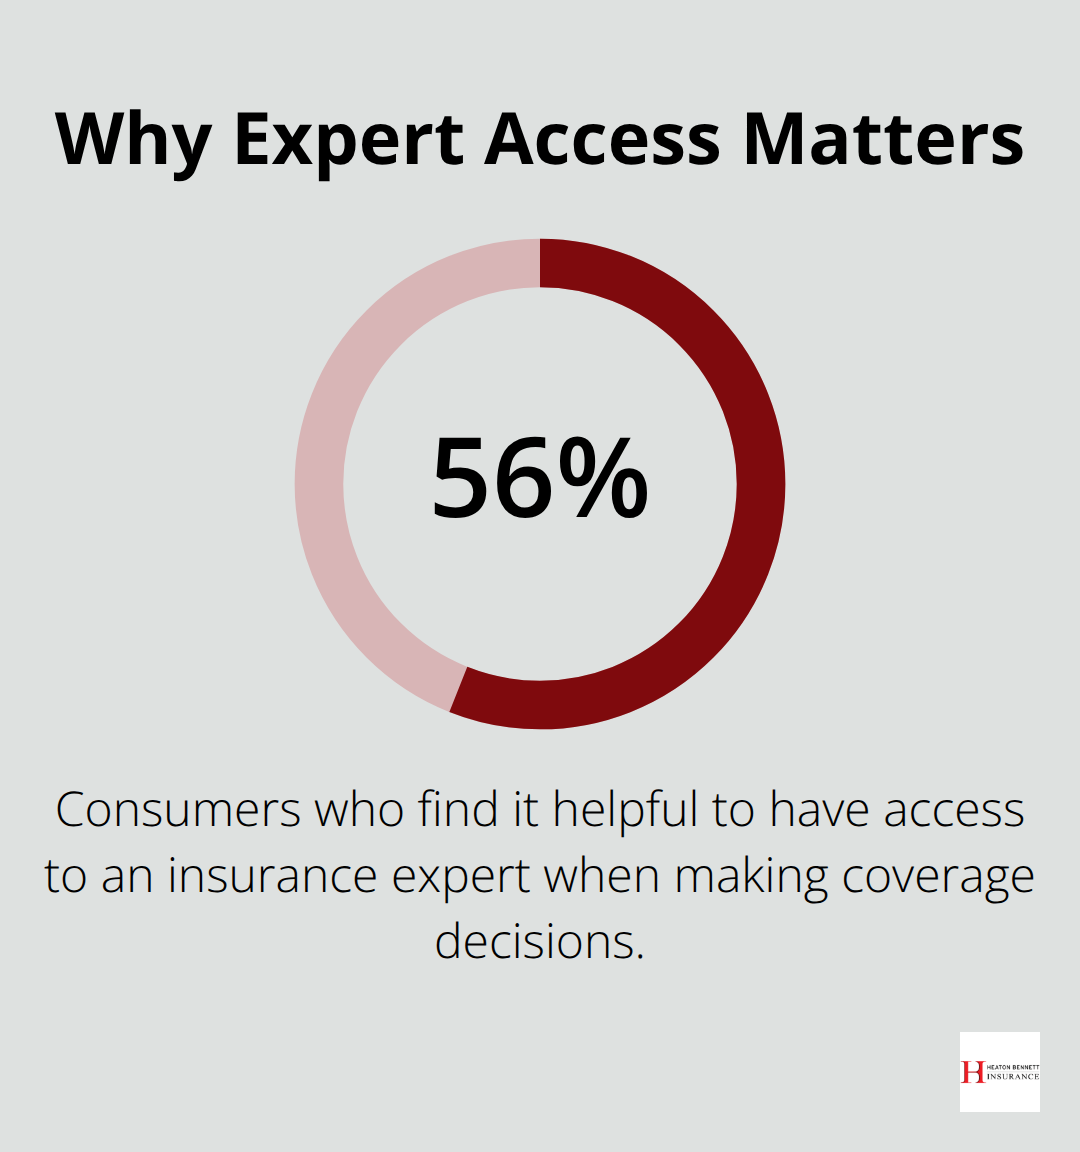
If a claim goes sideways, independent agents have the authority to advocate with multiple carriers on your behalf, not just one. They conduct proactive policy reviews to identify gaps before they become expensive problems. They remain available during evenings and weekends because their business model rewards responsiveness, not corporate efficiency metrics. Studies from The Hanover, which has partnered with independent agents for over 165 years, show that 56 percent of consumers find it helpful to have access to an insurance expert when making coverage decisions. Independent agents are that expert, and unlike captive agents, they have no conflict of interest pushing you toward unnecessary coverage or premium features that benefit the insurance company more than you.
Why This Matters When You Need Help Most
The difference between captive and independent service becomes most apparent during claims. A captive agent works for the insurance company, which creates an inherent conflict when you need that company to pay out. An independent agent works for you, which means they advocate for your interests throughout the entire claims process. This alignment of interests (your agent’s success depends on your satisfaction) transforms how problems get resolved and how quickly you receive support.
How Independent Agents Actually Simplify Your Insurance
Independent agents cut through insurance complexity by doing the work most people avoid. Rather than spending hours comparing quotes online or sitting through sales pitches designed to upsell you, independent agents conduct a thorough assessment of your actual situation and present options that match your real needs. This starts with understanding what you own, what risks matter most, and what coverage gaps exist in your current policies.
Assessment That Reveals What You Actually Need
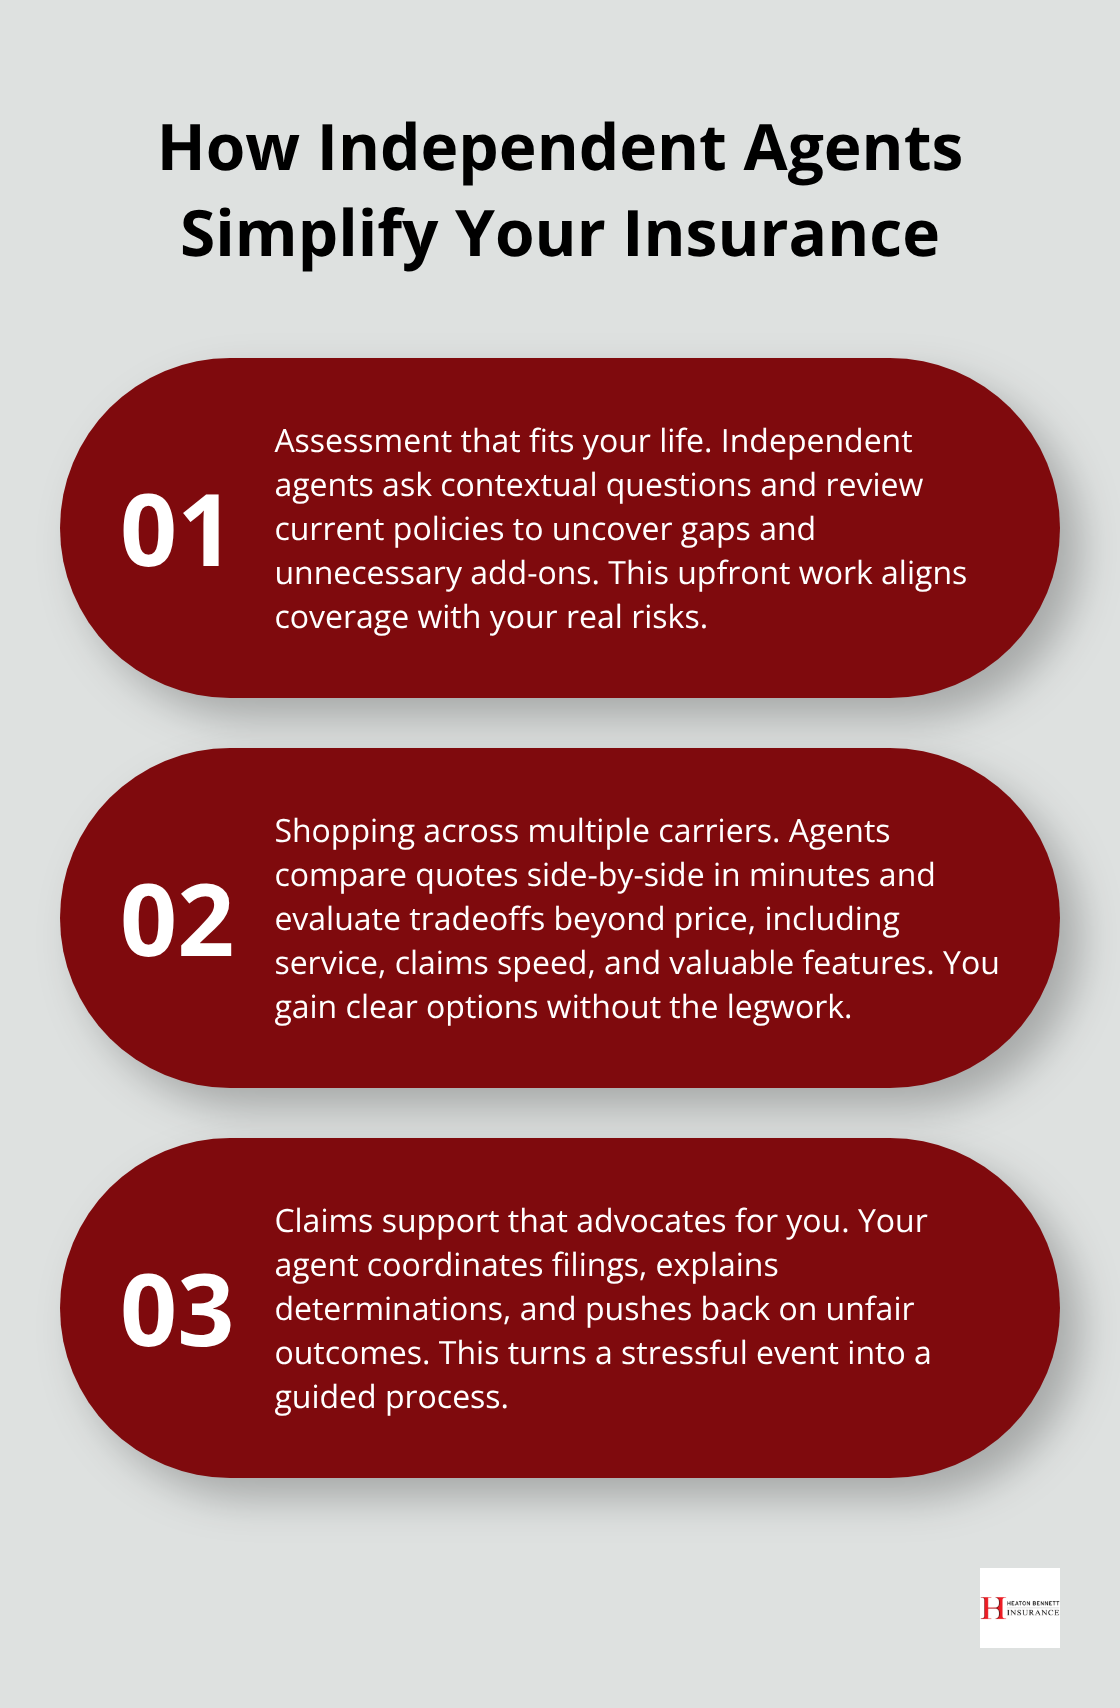
Most online quote tools ask generic questions and spit out standard answers. Independent agents ask follow-up questions that reveal what matters to you specifically-whether that’s protecting a new vehicle, covering a home renovation, or ensuring your business has adequate liability protection. The assessment phase typically uncovers coverage you didn’t know you needed. A homeowner might realize their standard policy excludes water damage from a burst pipe, or a small business owner might discover they lack umbrella coverage for liability claims exceeding their general liability limits. These gaps rarely surface through online shopping because algorithms cannot ask contextual questions. Independent agents identify these vulnerabilities before they become expensive problems.
Shopping Across Multiple Carriers Without the Legwork
Once an independent agent understands your needs, they compare quotes across their carrier network simultaneously rather than forcing you to request quotes separately from each company. This saves hours of form-filling and phone calls. Independent agents typically represent five to eight different insurance companies, meaning they can present genuine options within minutes instead of days. The comparison goes beyond price alone. An agent might show you that Company A offers the lowest premium but Company B provides superior customer service ratings and faster claims processing, while Company C includes features like accident forgiveness or loyalty discounts that better fit your situation. You see the tradeoffs clearly instead of choosing based on whichever quote landed in your inbox first.
Independent agents also leverage their relationships with carriers to negotiate better rates than you would find shopping alone. Carriers reward agents who bring consistent business with preferred pricing, discounts, and underwriting flexibility that direct consumers simply cannot access.
Claims Support That Actually Works
When a claim happens, most people discover that their insurance relationship was transactional, not protective. An independent agent transforms this moment by serving as your advocate throughout the entire process. They file claims on your behalf, follow up with the insurance company, explain coverage determinations, and push back if a claim denial seems unjustified. This matters enormously because insurance companies employ claims adjusters trained to minimize payouts within policy language, and without someone in your corner, you may accept an unfavorable settlement without realizing you had stronger ground to negotiate.
Independent agents handle the coordination between you and the carrier, reducing stress during an already difficult time. They also conduct periodic policy reviews to prevent coverage lapses that could prove catastrophic during a claim. A business owner might renew their general liability policy annually without realizing their revenue has grown and their coverage limits are now inadequate, leaving them exposed to claims that exceed their policy maximum. An independent agent catches this during a review and recommends adjustments before disaster strikes. This proactive approach transforms insurance from a reactive expense into a protective partnership that evolves as your life and business change.
Coverage That Fits Your Actual Situation
Personal Lines: Home and Auto Protection Tailored to Your Risk
Independent agents refuse to sell you a one-size-fits-all policy because your situation is unique. A homeowner with a mortgage, two vehicles, and a side business needs something completely different from a renter with one car and minimal assets. This is where independent agents separate themselves from online quote tools and captive agents who push standardized packages. They start by asking what you actually own, what risks keep you awake at night, and what gaps exist in your current coverage.
For personal lines, this means understanding whether your home sits in a flood zone, whether you have expensive jewelry or electronics that standard policies exclude, or whether you need specific coverage for a newly licensed teenage driver. A standard homeowners policy covers dwelling, personal property, and liability, but it often excludes water damage from burst pipes, damage from earthquakes or floods, and valuable items like art or antiques. An independent agent identifies these exclusions during the assessment phase and recommends additions like water backup coverage or a scheduled personal property rider.
For auto insurance, the same principle applies. Most people buy whatever coverage their lender requires and call it done, but an independent agent asks whether you commute 50 miles daily on highways (suggesting higher liability limits) or drive locally around Austin (potentially allowing lower limits). They ask whether you have significant assets to protect, which determines whether you need umbrella coverage starting at $1 million in additional liability protection.
Business Coverage: Protection That Matches Your Operations
For business owners, the assessment becomes even more critical because the wrong coverage choice can bankrupt the company. A contractor needs general liability, workers compensation if they have employees, tools and equipment coverage, and vehicle coverage for work trucks. A service-based business like a consulting firm needs professional liability insurance, which protects against claims that your advice caused financial harm to a client. An e-commerce business needs cyber liability coverage because a data breach exposing customer information can trigger lawsuits and regulatory fines.
Without an independent agent asking detailed questions about operations, revenue, and risk exposure, business owners often carry inadequate coverage or pay for protection they do not need. Independent agents work directly with carriers to understand classification codes, payroll structures, and industry-specific risks that dramatically affect pricing and coverage availability.
Specialized Coverage Most People Cannot Find Alone
Independent agents handle specialized coverage that most people do not know exists or cannot find through standard online channels. Motorcycle insurance requires different underwriting than auto insurance because motorcycles carry higher injury risk and different claims patterns. Vacant property coverage protects buildings between tenants or during renovation, which standard homeowners policies explicitly exclude. Landlord policies cover rental properties with liability and loss-of-rent provisions that residential policies lack.
For businesses, workers compensation varies dramatically by industry classification, payroll size, and claims history, making quotes nearly impossible to obtain without an agent working directly with carriers. When you need motorcycle coverage in Austin, an agent who represents multiple carriers can quote you through companies that specialize in motorcycle risk rather than forcing you into a standard auto policy rider that costs more and covers less. When a small business owner needs workers compensation, an agent can negotiate classification codes with carriers that accurately reflect the work performed, potentially saving thousands in annual premiums through proper categorization.
This practical knowledge and carrier access transform insurance from a frustrating checkbox into a tool that actually protects what matters most.
Final Thoughts
The insurance industry profits when you stay confused and isolated, but how independent agents operate transforms this dynamic entirely. Your agent’s success depends on your satisfaction and retention, not on pushing unnecessary coverage or locking you into a single carrier’s limitations. Independent agents negotiate better rates, identify coverage gaps before they become expensive problems, and advocate fiercely during claims because their income and reputation rest on your trust.
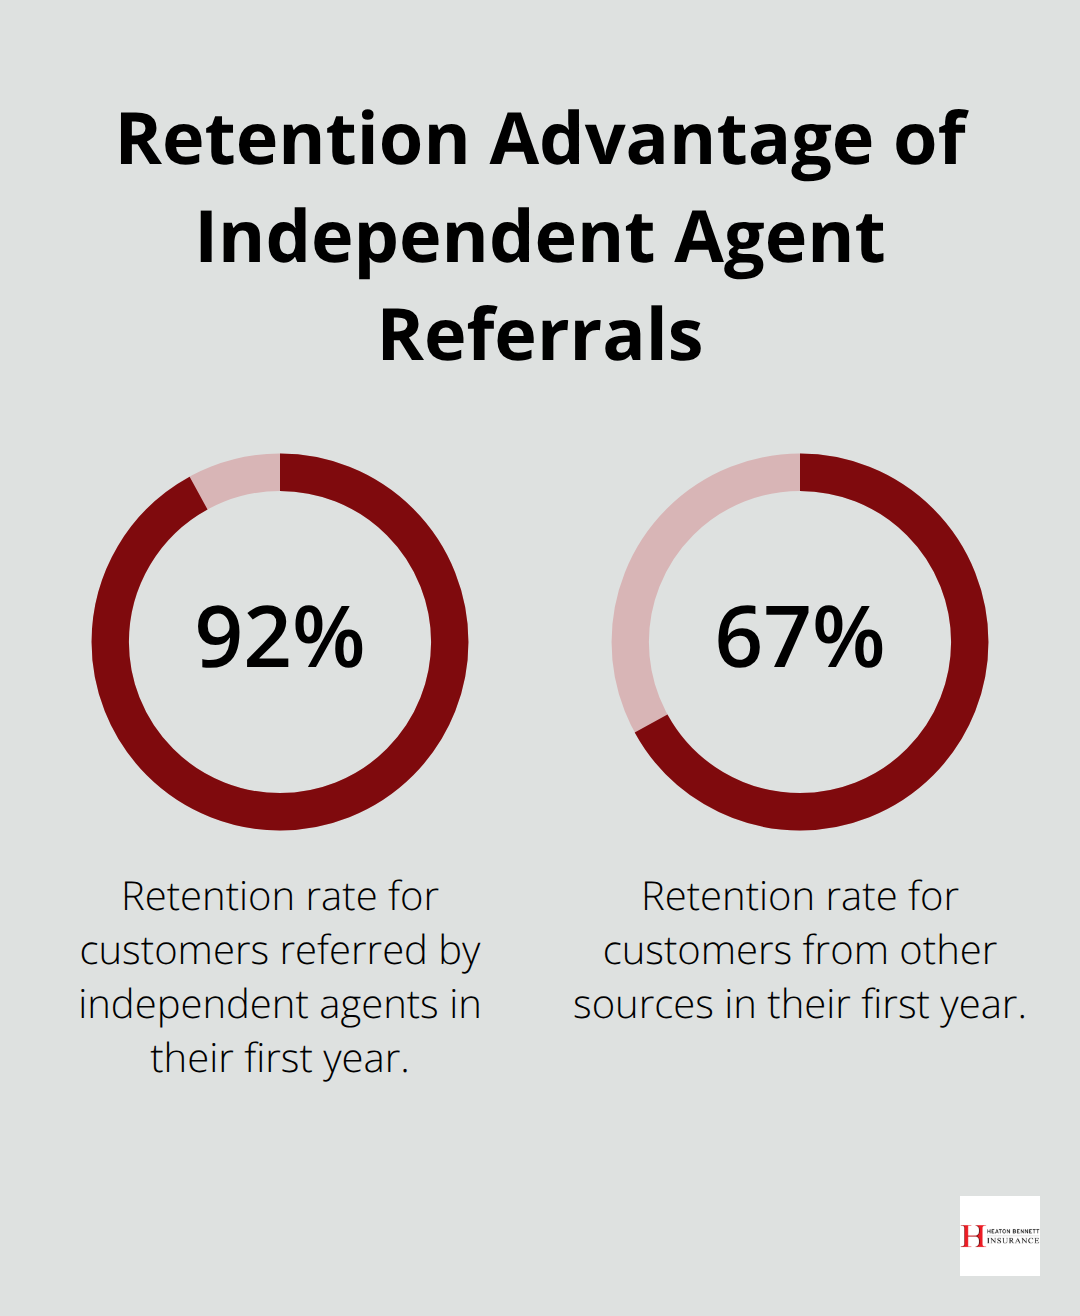
We at Heaton Bennett Insurance have spent years helping Austin residents and business owners experience what genuine choice actually means. Referred customers from independent agents generate five times more revenue in their first year and maintain 92 percent retention rates compared to 67 percent from other sources-a gap that reflects real, measurable value. Long-term partnerships compound these advantages as your agent learns your situation deeply and anticipates your needs before you recognize them.
Stop accepting whatever a captive agent offers and start demanding the choice and care you deserve. Heaton Bennett Insurance brings independent agent advantages to Austin with access to multiple carriers, personalized coverage assessments, and expertise across personal and business insurance.
The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation.
